Dr Carsten Sander Christensen, Danish Contributor to Azerbaijan Today Magazine.
The morning after the 2026 U.S. midterm elections, a palpable sense of relief washed through the corridors of the Berlaymont in Brussels and the chancelleries of Berlin and Paris. With Democrats successfully wresting control of both the House and the Senate, the prevailing narrative was one of restoration. The logic seemed sound: a “lame duck” president, now shackled by a hostile legislature, would surely have to moderate his “America First” agenda. The era of erratic trade wars, many hoped, had hit a legislative brick wall.
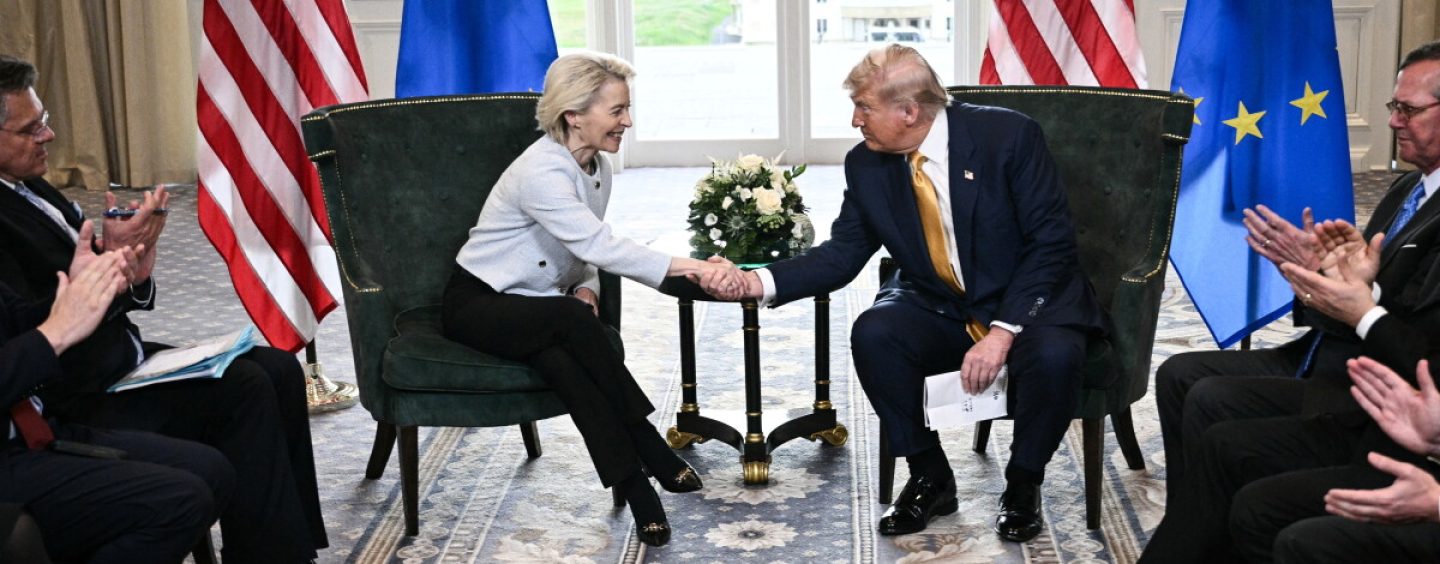
However, as the dust settles on the electoral map, a far grimmer economic reality is emerging. For Europe, the Democratic sweep is not a reprieve; it is a catalyst for a more volatile brand of transatlantic friction. The economic plot of 2027 will not be defined by a return to multilateral norms, but by “trade displacement.” Constrained at home by a Congress that will block his domestic agenda at every turn, the President is likely to turn his gaze—and his executive pen—toward the one arena where he remains largely unchecked: international trade.
The Executive Paradox
The European miscalculation lies in a fundamental misunderstanding of the American separation of powers. While Congress holds the “power of the purse” and legislative oversight, the President retains formidable, direct executive authority to impose tariffs under statutes such as Section 301 of the Trade Act of 1974. In a period of domestic gridlock, trade policy becomes a path of least resistance for an embattled executive. As one senior European diplomat observed, “If the President cannot build a wall or pass a budget, he will inevitably turn to the files where parliamentarians have less influence.” For the White House, the European Union represents a target-rich environment of trade surpluses and industrial competitors. Rather than moderating, the administration is incentivized to sharpen its tariff agenda to demonstrate strength to a domestic base that feels the legislative process has failed them.
Front One: The Ticking Clock of 2026
Europe now finds itself caught in a two-front economic squeeze, the first of which is a looming deadline that Congress is powerless to move. While the so-called “Turnberry framework” managed to cap many EU goods at a 15% tariff rate, it left the most contentious sectors—steel and aluminum—in a state of high-altitude suspension. U.S. duties on these metals remain as high as 50%, a protectionist legacy that continues to bleed European manufacturers. The critical inflection point is December 31, 2026. On this date, the EU’s “safety valve” mechanisms are set to expire. If Washington does not significantly lower these metal duties by the end of the year, Brussels will be legally and politically compelled to suspend its own tariff concessions.
The new Democratic Congress may hold hearings, issue stern statements, and express disapproval of further escalation, but they cannot legally force the President’s hand on Section 232 national security tariffs before the deadline. This creates a high-stakes game of chicken. Europe must decide whether to retaliate against a U.S. economy already struggling with a $2 trillion budget deficit and stubbornly elevated energy costs. Such a move would almost certainly trigger a tit-for-tat escalation—an outcome the President is now structurally freer to pursue, as he has no domestic legislative agenda left to protect from political blowback.
Front Two: The German Transmission Channel
If steel and aluminum are the simmering tension, the automotive sector is the potential explosion. Throughout 2026, the threat of a 25% tariff on European cars has been used as a recurring cudgel in negotiations. This threat targets the very heart of the European industrial core: Germany. The economic projections are harrowing. The Kiel Institute estimates that such a tariff would result in short-term output losses of at least €15 billion for the German auto sector alone. In the long term, as supply chains adjust and investment flees, that figure could balloon to €30 billion.
Because Germany serves as the EU’s economic locomotive, a shock to its automotive industry acts as a contagion. The “German transmission channel” ensures that a tariff on a factory in Stuttgart is felt by a parts supplier in Poland, a software firm in Romania, and a shipping port in the Netherlands. Current estimates suggest that these US tariffs could shave a full 0.5 percentage points off total EU GDP growth in 2027. Small, open economies like Ireland and the Nordic nations, which are deeply integrated into transatlantic value chains, remain among the most exposed to this volatility.
The Illusion of Symmetry
The bitter irony for Europe is that while the Democratic victory may improve the tone of transatlantic relations, it does nothing to fix the structural asymmetry of the relationship. A Democratic Congress might favor a more diplomatic rhetoric, but it shares many of the same protectionist instincts regarding green energy subsidies and Chinese decoupling that the executive branch champions. The White House continues to weaponize uncertainty. By changing tariff lines overnight or linking trade concessions to non-trade demands—such as increased defense spending or changes to digital services taxes—the administration forces European firms into a defensive crouch.
Ultimately, Europe’s post-midterm relief was an economic illusion. The continent is no longer facing a predictable adversary that can be reasoned with through legislative channels. Instead, it faces a domestically constrained President who views the Atlantic not as a bridge to allies, but as a theater for executive action. As 2027 approaches, Brussels must realize that the “Blue Wave” in Washington has not cleared the storm clouds over the European economy; it has simply changed the direction of the wind.